-
Continue reading →: Suntec REIT 2026 Restructuring: Evaluating Hongkong Land’s Entry and New Sponsor Dynamics
Executive Summary This article covers the operational and strategic transformation of Suntec REIT (SGX: T82U) following a macroeconomic pivot toward rate cuts and the transition of management control to the Tang family’s Acrophyte Asset Management. It addresses why the real estate investment trust’s high proportion of unhedged debt, previously a…
-
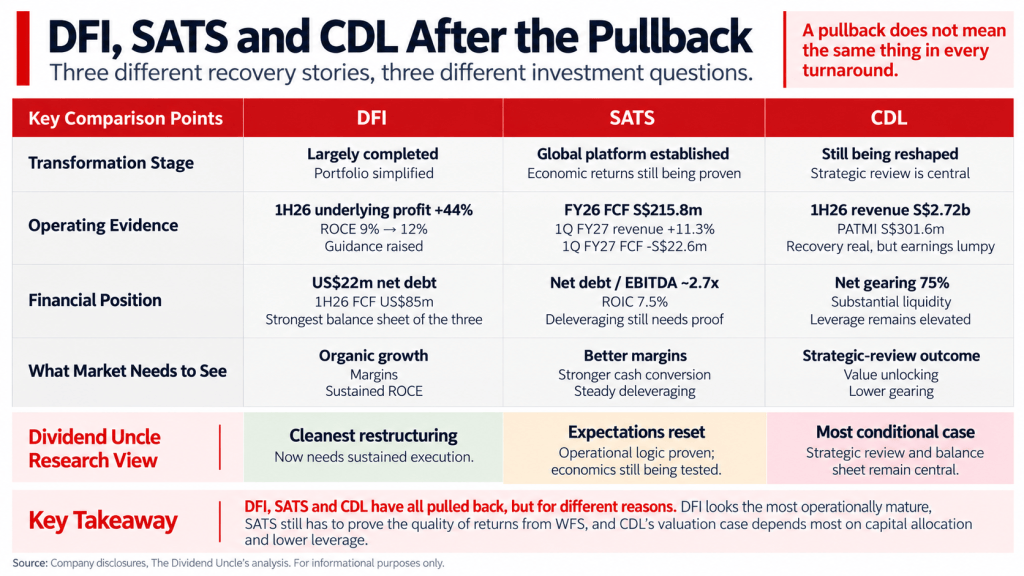
Continue reading →: DFI and SBS Transit: Analyzing Special Dividend Sustainability and Growth Trajectories
Executive Summary This article examines the recent surge in special dividends within the Singapore market, focusing on the divergent fundamentals of DFI Retail Group (SGX: D01) and SBS Transit (SGX: S61). While both companies have utilized large capital returns to reward shareholders, the underlying business trajectories suggest very different outcomes…
-
Continue reading →: CICT’s S$6.4 Billion Portfolio Reconstitution: Analyzing the Asia Square for Paragon Asset Swap
Executive Summary CapitaLand Integrated Commercial Trust (CICT) (SGX: C38U) has announced a significant S$6.4 billion portfolio reconstitution, marked by the divestment of Asia Square Tower 2 and the acquisition of the freehold flagship asset, Paragon. This move represents a strategic shift from leasehold office exposure in Marina Bay to high-traffic…
-
Continue reading →: Evaluating Singapore Aviation Dividend Stocks: SIA, SATS, and SIAEC
Executive Summary The Singapore aviation sector is transitioning from a straightforward post-pandemic recovery into a complex phase characterized by divergent cash flow quality. While direct carriers initially benefited from surging passenger demand, the structural dynamics between airborne operations and ground infrastructure have shifted significantly. The sector now demands a more…
-
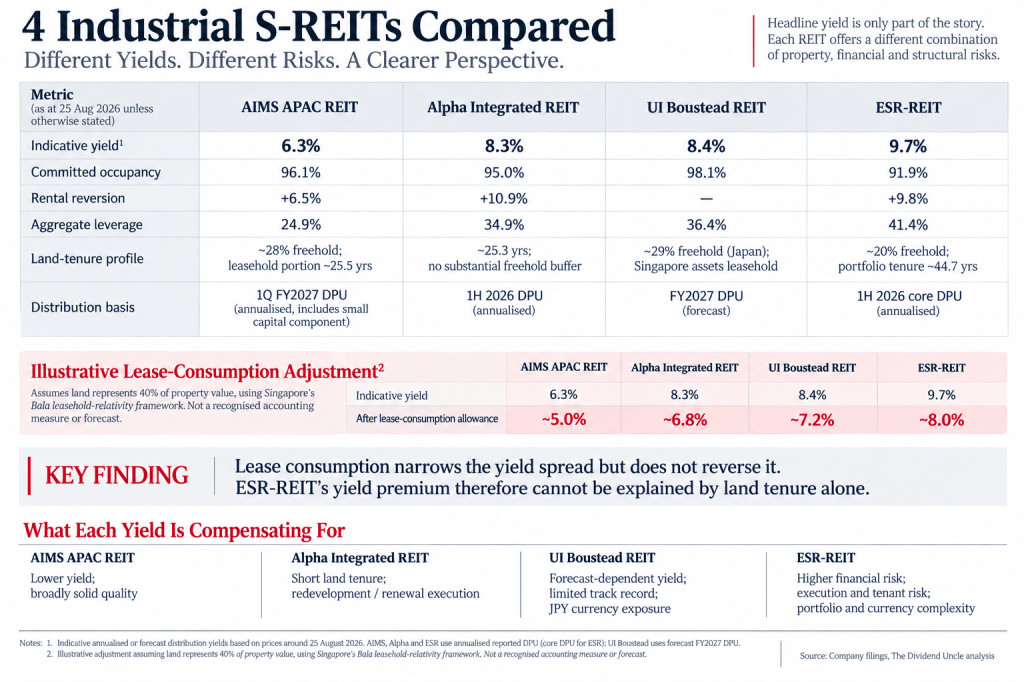
Continue reading →: 3 Singapore REITs Plunged Below Offer Prices: A Strategic Evaluation of Keppel, Lendlease, and UI Boustead
Executive Summary As of the second quarter of 2026, the Singapore Real Estate Investment Trust (S-REIT) market is navigating a period of significant technical pressure. Three major capital market events—the $1.02 billion IPO of UI Boustead REIT (SGX: UIBU), a $196.6 million preferential offering by Lendlease Global Commercial REIT (SGX:…
-
Continue reading →: Mapletree Logistics Trust Analysis: Evaluating Valuation and China Risks in 2026
Executive Summary Mapletree Logistics Trust (MLT) (SGX: M44U), long considered a blue-chip staple of the Singapore REIT (S-REIT) sector, is currently navigating a period of significant market pessimism. Recent financial results have highlighted a “perfect storm” of headwinds, including severe foreign exchange translation losses, a structural downturn in the Chinese…
-
Continue reading →: Evaluating Singapore Defensive Stocks: Sembcorp, Sheng Siong, ST Engineering, and NetLink in 2026
Executive Summary As macroeconomic uncertainty and geopolitical tensions elevate market volatility in early 2026, investors are increasingly rotating capital into traditional defensive equities. This search for structural safety often directs focus toward domestic utilities, consumer staples, engineering conglomerates, and commodity players, operating under the assumption that historically resilient business models…
-
Continue reading →: S-REITs Pull Back Again: Are Prices Disconnecting from Fundamentals?
Executive Summary Singapore REITs have retreated in early 2026 as bond yields moved sharply higher and expectations for rate cuts were pushed back. The sector’s decline—driven largely by macro repricing—has raised a key question: are falling REIT prices signalling deteriorating fundamentals, or simply reflecting a higher cost of capital? This…
-
Continue reading →: CLAR Preferential Offering: Should You Subscribe (vs Lendlease REIT Comparison)
Executive Summary CapitaLand Ascendas REIT (CLAR) (SGX: A17U) recently launched its equity fund raisings with its private placement was oversubscribed, while Lendlease Global Commercial REIT’s (SGX: JYEU) preferential offering saw weak take-up. This divergence reflects a more selective S-REIT market, where capital is directed toward scale, clarity, and credible growth…
-
Continue reading →: Elite UK REIT Lease Re-Gear: From a 95% Expiry Cliff to a More Durable Income Profile
Executive Summary Elite UK REIT’s (SGX: MXNU) investment case has shifted materially following a major lease re-gear with its primary tenant, the UK government. Previously, the REIT faced a concentrated lease expiry risk in 2028, where nearly all income was due for renewal at once—creating a structural “cliff” that weighed…

Independent research and analysis on Singapore-listed REITs and income-oriented investments, with a focus on long-term portfolio construction and income durability.
Read our Editorial Standards & Disclaimer ->
Welcome to ‘The Dividend Uncle’s Take’ — where I share clear, independent insights on Singapore REITs, dividend stocks, ETFs, and income-focused investing. Everything I write is grounded in my own research and real investing experience. No hype — just long-term thinking and skin in the game. Let’s grow our income portfolios steadily, one dividend at a time.
Let’s connect
Join the journey!
Stay updated with our latest articles and videos by joining our YouTube and other social media accounts.